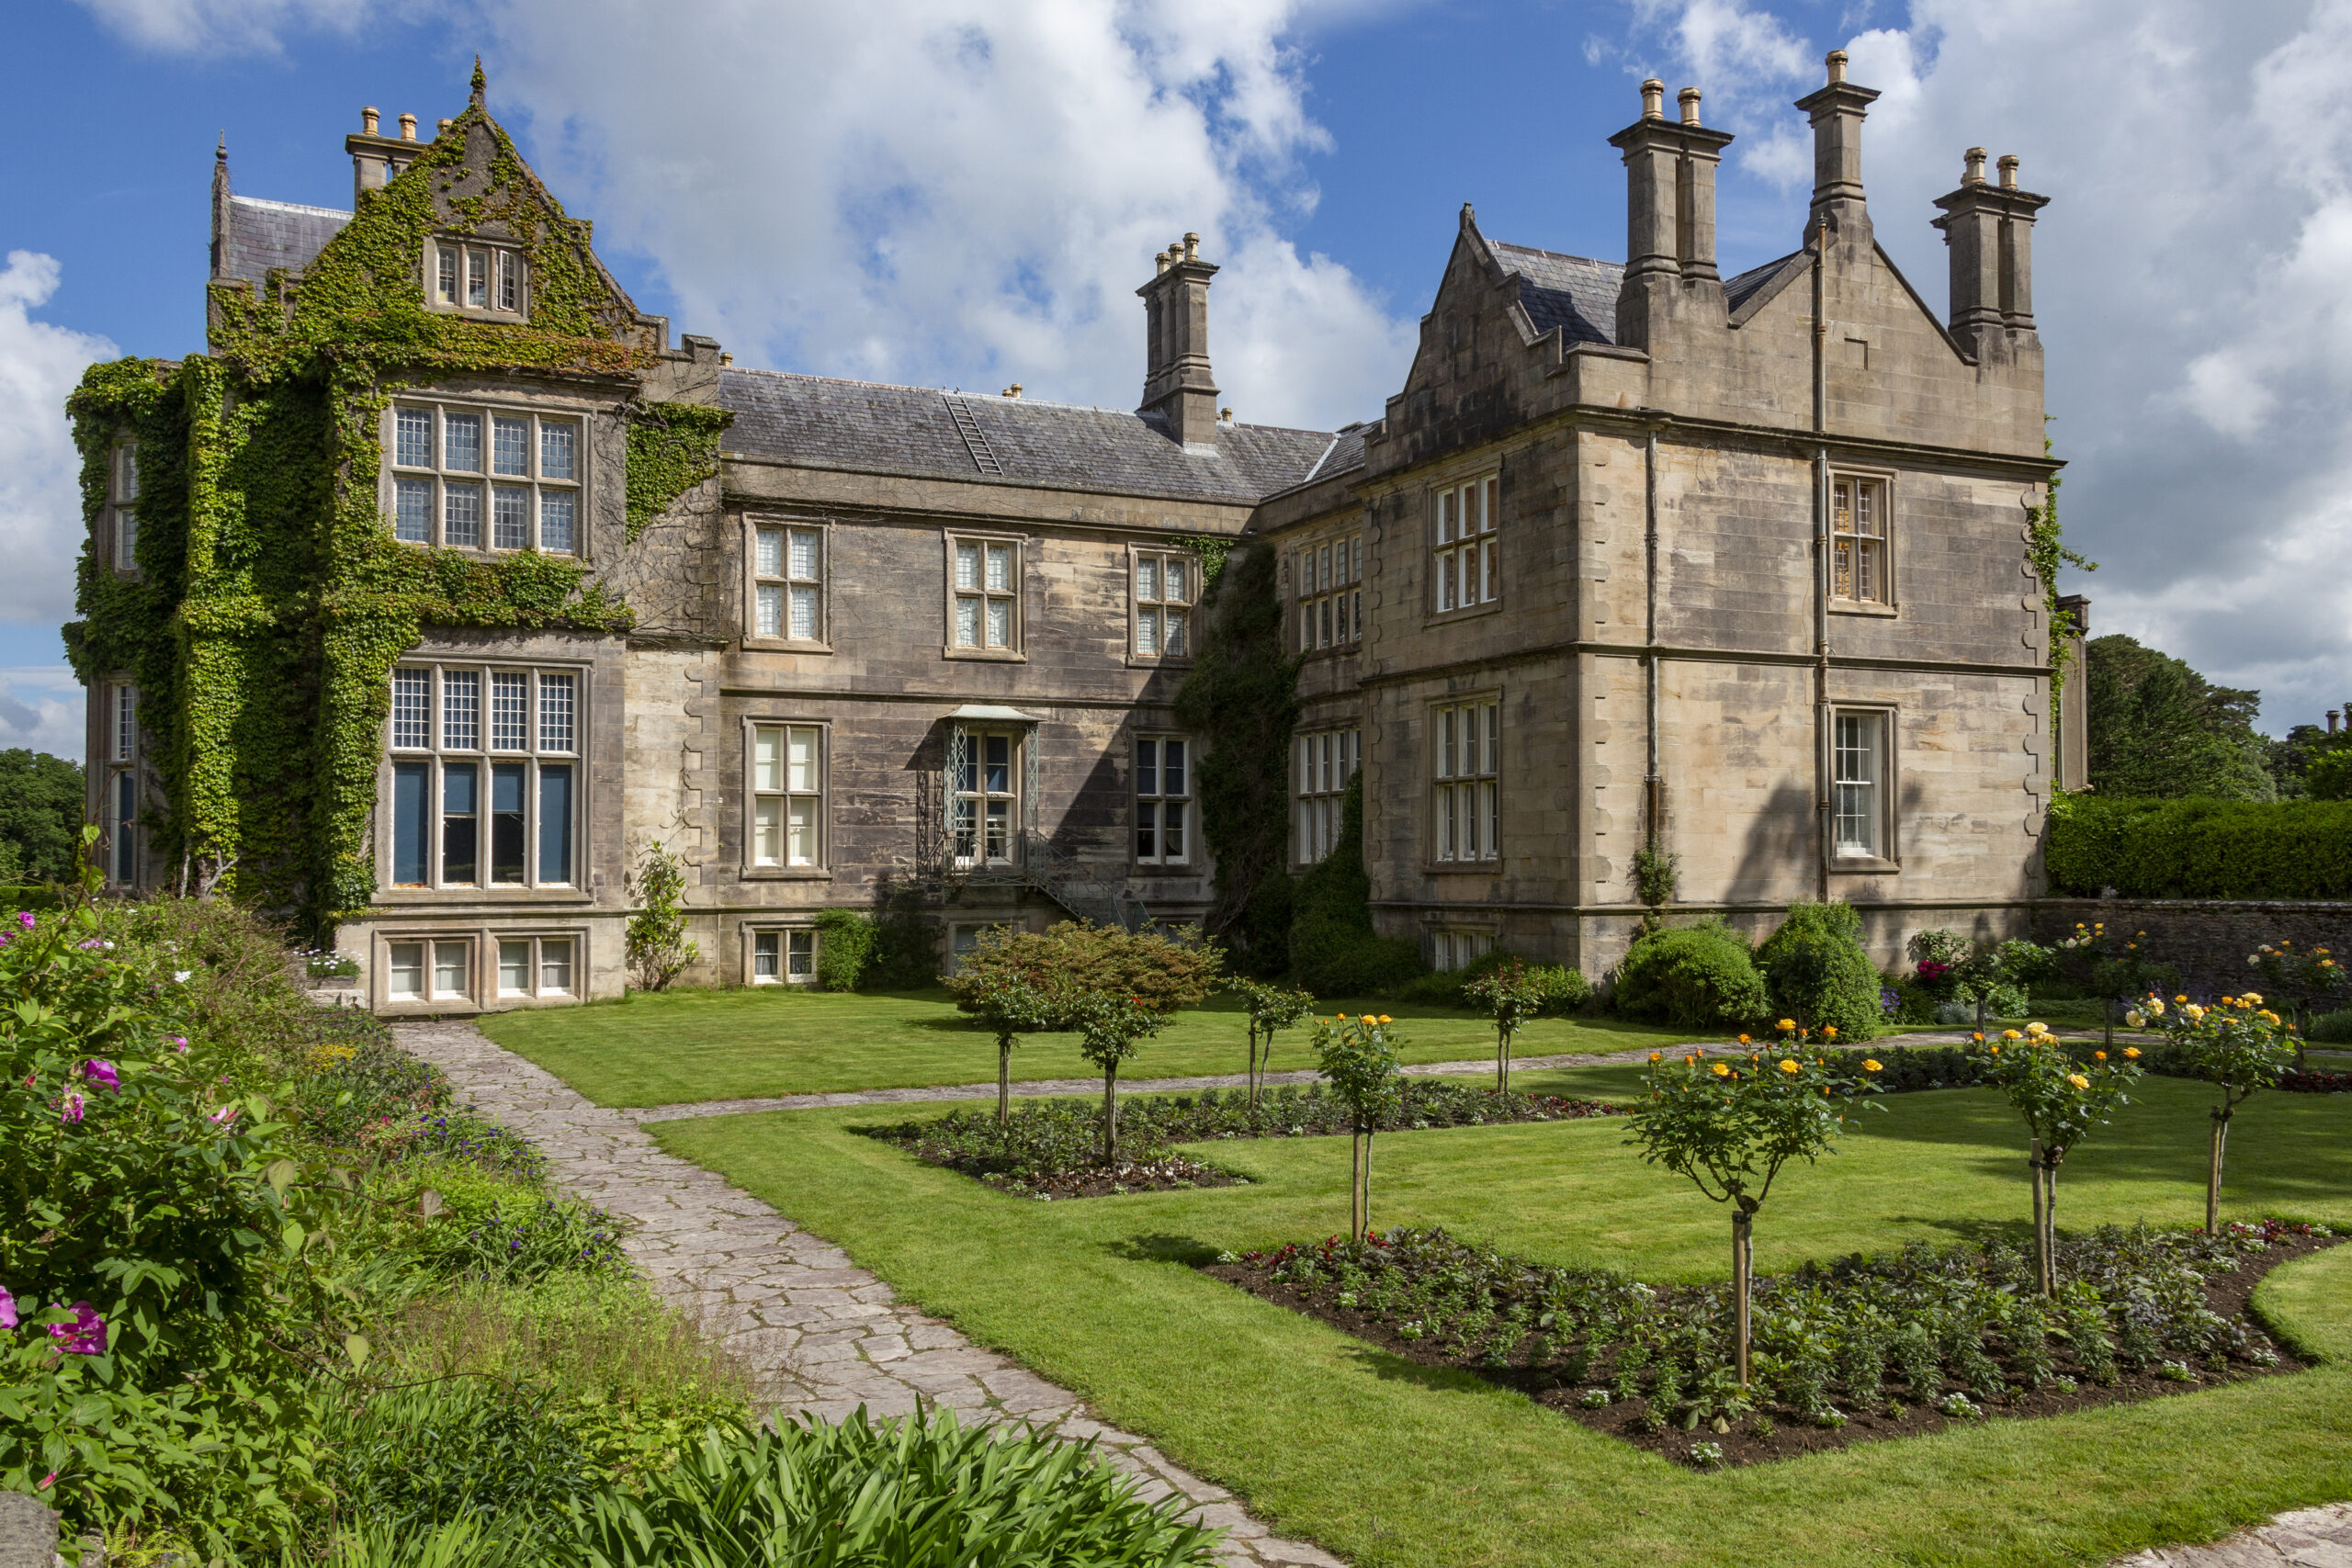
There has been increasing discussion about the proposed so-called “Mansion Tax” and, more recently, speculation that the threshold could eventually be reduced from £2 million to £1.5 million.
Whatever one’s political view of the proposal, I think there is a practical issue here which is in danger of being overlooked.
Owning An Expensive House Does Not Necessarily Mean That You Have A High Income.
As a Chartered Surveyor and Registered Valuer working predominantly in London and the Southeast, I regularly come across people who have owned their homes for many years. They may have bought them when values were a fraction of what they are today and, through nothing more than the passage of time and the extraordinary growth in property values, now find themselves living in a house worth £1.5 million, £2 million or more.
On paper they are wealthy. In terms of disposable income, the position can be very different.
This is particularly relevant to people approaching or already in retirement. Their home may represent the majority of their accumulated wealth, while their actual income is relatively modest or fixed.
Is A £1.5 Million House Really A “Mansion”?
This is where geography becomes important.
In some parts of the country, £1.5 million will undoubtedly buy a very substantial property. In London and much of the South East, however, it can buy something rather less extraordinary.
Indeed, in certain locations it may simply represent a good family house which has remained in the same ownership for many years.
A national threshold based purely upon capital value will therefore have a very different effect in Surrey or London than it will in other parts of England. That seems to me to be an important consideration when judging who this tax will actually affect.
Then We Come To Valuation
This is the part which particularly concerns me professionally.
Higher-value residential property is frequently difficult to value accurately without inspecting it.
Once we get into the £1.5 million to £2 million-plus market, properties tend to become increasingly individual. Two houses in the same road can have significantly different values because of their condition, plot, extensions, quality of accommodation, outlook, parking, setting and any number of other factors.
This is why I have reservations about relying too heavily upon desktop property valuation techniques.
A computer can analyse transactions. A valuer can analyse the property.
There is a difference.
If a tax liability turns upon whether a house is worth, say, £1.48 million or £1.52 million, that distinction suddenly becomes extremely important.
And inevitably there will be properties sitting very close to whatever threshold is finally adopted.
I Suspect Valuation Appeals Could Become A Major Issue
If large numbers of properties are assessed using a mass or desktop valuation exercise (as it is understood HMRC/VOA intend to do) I would expect a significant number of owners to question the resulting figures.
That does not mean every assessment will be wrong. Far from it.
But where an individual property is close to a taxation threshold, I believe owners should be prepared to look carefully at the evidence upon which the valuation has been based.
An independent valuation undertaken by a suitably qualified valuer who has actually inspected the property may become extremely important.
My concern is that, once assessments start arriving, the system could become very busy very quickly.
So Should Homeowners Do Anything Now?
There is no need to panic.
The speculation surrounding a possible £1.5 million threshold is just that at present, and the final rules and procedures need to be seen before anybody makes significant decisions.
However, owners of properties which are likely to sit close to the eventual threshold should, in my view, start paying attention.
Keep records of significant works to the property. Be aware of genuinely comparable sales in your locality and, when the valuation date and appeal procedure become clear, consider whether obtaining your own professional valuation would be sensible.
The important point is not to assume that an official valuation must automatically be correct.
Property valuation is an opinion of value based upon evidence and professional judgement. Where that opinion results in an ongoing tax liability, homeowners are perfectly entitled to understand how it has been reached and, where appropriate, challenge it.
Property-Rich Does Not Necessarily Mean Cash-Rich
For me, this remains the biggest issue.
There will undoubtedly be people caught by this tax who are wealthy by almost any reasonable definition and who can comfortably afford the additional annual cost.
But there will also be longstanding homeowners, particularly in London and the South East, whose circumstances are quite different.
They have not necessarily chosen to become owners of a £2 million asset. The market has simply moved around them.
That distinction between asset wealth and available income deserves rather more attention than it has received so far.
I shall be watching the proposals closely over the coming months, particularly the valuation and appeals process, and will provide further updates as the position becomes clearer.
Nick Hanson FRICS
Chartered Surveyor & Registered Valuer
Vospers Friend & Falcke
Image Source: Envato


